Hops, price and portfolio: three clues to how beer is changing
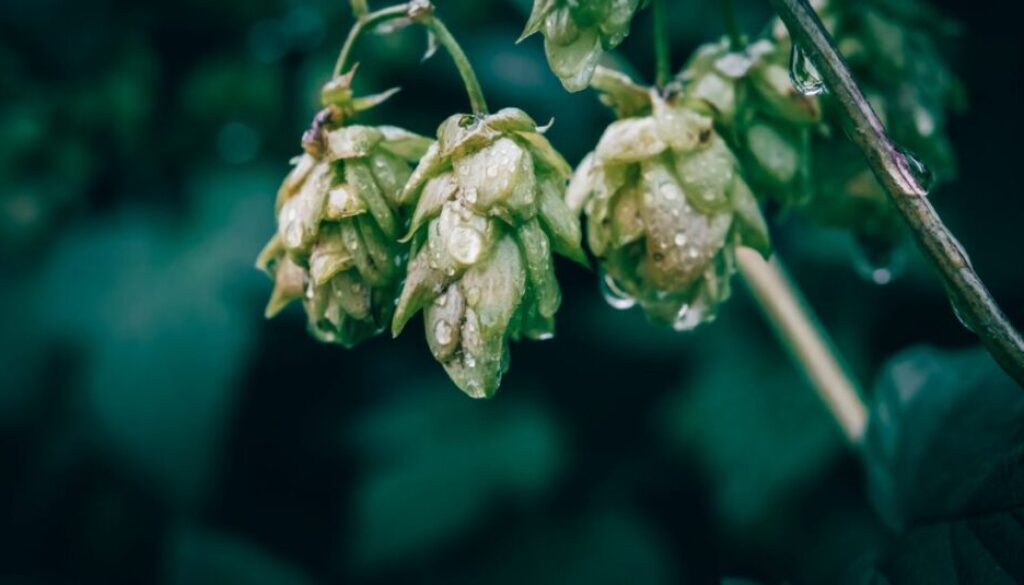
Some shifts in beer make more sense once they stop looking like exceptions and start reading like clues. One is BridgePort’s new IPA, released in Portland, Oregon, in 1996: a local brewery, a very clear idea of what hops could do, and a beer that helped bring attention to the aromatic profile of American cultivars, especially Cascade. The project was shaped with input from Australian brewer Phil Sexton and Karl Ockert, two figures tied to a transitional moment that feels almost obvious now, but was anything but at the time.
That IPA matters not only as a historical footnote. It shows how categories become established when someone finds the right language for them, before the market fully catches up. The beer won major awards and became BridgePort’s signature beer. Years later, the brewery closed in 2019, but the story remains useful as a way to read a broader shift: the moment American hops began to be seen not as a local variation on European brewing, but as an aromatic language of their own.
Prices under pressure
The second clue comes from Germany, where beer is going through a period of intense promotional pressure. Some offers push well-known crate packs below the 10-euro mark, and that continues to put strong pressure on higher-priced regional breweries. This is not the story of a sudden collapse, but of a steady squeeze that makes it harder to defend value outside major retail campaigns.
The issue is not only the depth of the discount, but the effect it has on perception. When price becomes the dominant message, beer risks being read mainly as a shelf product rather than as a style, a place or a producer identity. That dynamic hurts smaller players, but it also says something broader about the relationship between buying habits and brand recognition.
Broader portfolios, more selective drinking
The third clue is visible in American distribution. Many beverage distributors are broadening their portfolios toward RTDs, non-alcoholic drinks and energy beverages, alongside classic beers. This is not just an assortment decision: it is a response to more fragmented drinking occasions and to a younger audience that appears to drink more selectively and less automatically.
Even here, it is worth avoiding overly linear readings. This is not about declaring the end of beer, nor about describing a clean substitution. What emerges instead is an ecosystem in which volume alone no longer explains the market. Distributors have to manage different categories, different occasions and different expectations, while producers are forced to decide how much to lean on familiarity and how much on differentiation.
Read together, these three cases do not point to a single, definitive thesis. They show, instead, how beer continues to move between innovation, price and consumption habits. An IPA built to showcase a hop can become a cultural reference; aggressive promotions can lower perceived value; a distribution portfolio can widen to capture more variable drinking moments. That tension, more than any neat formula, is where the sector is being decided today.