Turkish tea grows beyond its home market, but the leap still looks fragile
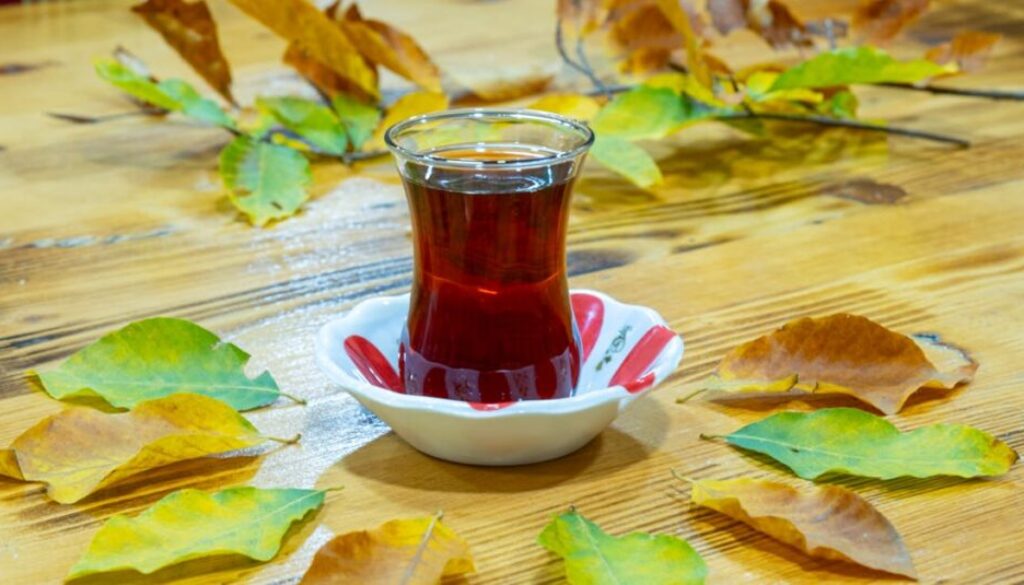
There is a country that has been producing tea for more than a century, consuming it at one of the highest per-capita rates in the world, and only in recent years trying to turn that habit into a more structured export project. Turkey is not the first place most people think of when tea turns international, yet the latest figures point to a clear shift in scale: last year, Turkish tea exports reached a record $34.8 million, up about 38% year on year, across 122 destinations including countries, autonomous regions and free trade zones.
Belgium is the main destination, with $12.7 million in purchases. Belgian demand is partly supported by large Turkish communities in Brussels and Antwerp; the country may also function as a redistribution point for nearby markets. The UK follows at some distance, with $5.8 million. These are still modest numbers in the context of the global tea trade, but the direction is telling: Turkish producers are trying to move beyond diaspora-led demand and find a place in broader markets, with packaged, branded products and a clearer identity on shelf.
The ambition is primarily European, but it also reaches toward the Middle East, North America and selected Asian markets. Doğuş Çay, Turkey’s second-largest producer, has announced an investment in a food manufacturing facility in Hungary with iced-tea lines, which the company presents as its first production site outside Turkey. Efor Çay, the third-largest producer by volume, is working to expand capacity. Çaykur, the state-owned company, has developed a herbal tea range and is experimenting with blends of local black tea and wild blueberries. Taken together, these moves suggest an industry trying to move away from bulk exports and build more value around finished products and brand identity.
A commercial leap that still needs firmer ground
For all that momentum, the picture is still more complicated than the record suggests. In Turkey, tea production costs appear higher than in many other producing countries, in part because raw-material costs account for a larger share of total costs. That can squeeze margins precisely when the sector is trying to compete in markets that are more price-sensitive and less forgiving on supply consistency.
At that point, the discussion is no longer just about trade. It also becomes a question of how a supply chain earns credibility. THIRST, an international platform focused on human rights in the tea supply chain, has recently opened a public conversation about what the tea sector can learn from other industries in terms of responsibility and transparency. That is not a ready-made model for Turkey, but it is a useful reminder: once an industry aims to grow in value and visibility, it has to balance pricing, product and conditions across the chain.
In that sense, the Turkish case is more a guide to what to watch than proof of a wider industry shift. The export record shows a sector trying to move toward packaged products and stronger brands; the sustainability of that growth will depend on whether the upstream side can hold up as well. It is a pattern familiar in other beverage categories, from specialty coffee to fine wine: trading up is possible, but only when added value is matched by a coherent foundation throughout the chain.
For Turkish tea, the point is not to prove that it can immediately compete with the biggest global names. For now, the real question is whether this export record marks the start of a more durable presence or only a favourable phase. The move from identity product to exportable brand is already meaningful. Turning it into a lasting model will be the harder part.