Whisky, three moves that point to different strategies
In whisky, the key question is not only what reaches the shelf, but how it gets there. Some labels lean on immediate flavours and an easier entry into the category; others reinforce the credibility of an age statement; still others try to balance heritage with contemporary taste. Three recent launches are enough to show how distinct those strategies can be.
The most straightforward example is Jack Daniel’s, the Tennessee brand owned by Brown-Forman. Jack Daniel’s Tennessee Apple crossed the one-million-case mark for the first time in 2025. That figure suggests that some flavored American whiskeys still have room to grow, especially when they offer an easy-to-read profile and fit more informal drinking occasions. It is not a signal for the whole category, but it does say something about this specific corner of the market.
At the other end sits Laphroaig, the Islay distillery associated with heavily peated, smoky single malts. The permanent return of its 15-year-old expression to the core range should be read as a statement of continuity rather than nostalgia. Putting a clearly aged whisky back at the centre of the portfolio means working on a long timeline, managing stock carefully and trusting consumers to value a more mature expression. In this case, the emphasis is not on easy access but on style consistency and the added depth an age statement can bring to the range.
When a blend looks for a different language
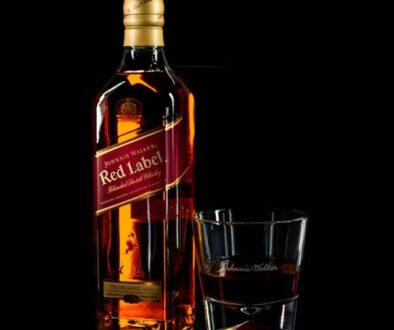
Between those two poles is Johnnie Walker, the blended Scotch from Diageo, which has introduced Black Cask as a new permanent expression matured exclusively in American white oak ex-bourbon barrels. Here too the message is clear enough: the brand is not abandoning its Scotch identity, but it is aiming for a softer, more vanilla-forward profile that can also speak to drinkers who prefer whisky neat, over ice or in classic cocktails.
The technique itself is not new. Scotch matured or finished in ex-bourbon wood has long been part of the category, so the point is not novelty for its own sake. What matters is the decision to make that approach a permanent part of the line-up rather than a one-off test. It suggests that some major brands are reading the American market with more attention to flavour profile than to origin alone, while still relying on the familiarity of their own names.
Read together, these three cases do not prove a single sector-wide shift. They show something more nuanced: whisky continues to move along several tracks at once, from accessibility to premiumisation to stylistic reinvention. Just as important, they remind us that the category cannot be described with one formula. There is room for products that lower the entry barrier, for whiskies that make age statements part of their value, and for blends that try to sound closer to today’s drinking habits.
The real question is not which path will win. It is how long brands can keep occupying different spaces without flattening one another. In a category this broad, whisky still seems able to hold different speeds in parallel — as long as each release knows exactly who it is for.